


Ohio Valley contractors heading into the second half of 2026 face a familiar squeeze: elevated material prices, labor shortages showing no signs of easing, and competitive bidding environments that leave little room for error. This article breaks down where construction profitability is leaking, which estimating and procurement habits are responsible, and what merit-shop contractors across Southwest and West Central Ohio, Northern Kentucky, and Southeastern Indiana can do right now to protect their bottom line.
Key Takeaways
- Net profit margin for most general contractors still sits between 1.5% and 5%, meaning a single mispriced project can erase an entire year’s profit in the current cost environment.
- Volatile material costs, including steel, copper, switchgear, and roofing membranes, remain well above pre-2020 baselines and continue to compress construction profit margins across the Ohio Valley.
- Smarter risk management through disciplined estimating, early procurement, escalation clauses, and structured bid review processes is the fastest way to increase profitability on commercial and industrial projects.
- Tracking labor productivity, change orders, and job costs in real time separates profitable businesses from those treading water at breakeven.
- ABC Ohio Valley offers training, workforce development, safety programs, and peer networks that help merit-shop contractors make informed decisions and protect margins across the region.
Why Construction Profitability Still Feels Tight in 2026
Even though some commodity spikes have cooled since 2021 and 2022, elevated input prices and trade-related tariffs can keep costs high, with producer price levels for key construction materials still roughly 20% to 35% above pre-2020 baselines. Construction material costs rose 6% year-over-year as of March 2026, and the Producer Price Index for construction materials hit 354.9 in 2026, reaching a new peak in April. That persistent elevation compresses profit margins on Ohio Valley construction projects regardless of whether the headline trend reads “stabilizing.”
In practical terms, construction profitability is the relationship between revenue, direct job costs (materials, labor, equipment, subcontractors), overhead, and the final net profit a company retains. Profitability in the construction industry often hovers in low single-digit net profit margins because competitive bidding, fixed-price contracts, and change risk leave little cushion. The average net profit margin for general contractors falls between 1.5% and 3%.
Consider a commercial general contractor in the Cincinnati or Dayton market producing $10 million in annual revenue at a 3% net profit margin. That firm earns roughly $300,000 after all costs, overhead, and taxes. If just two mid-size projects absorb a 2% to 3% material cost overrun each, the year’s net profit can disappear entirely. That is not a theoretical exercise; it is a pattern many contractors in the Ohio Valley recognize.
This article focuses on what merit-shop contractors can do in 2026 to bid smarter, manage material and labor risk, and keep money on the bottom line instead of losing it to preventable leakage.
Understanding Net Profit, Net Profit Margin, and Where Construction Profit Margins Disappear
Net profit is the amount remaining after subtracting every cost, including direct job costs, overhead, and taxes, from total revenue. The net profit margin calculation is straightforward: (Net Profit / Revenue) x 100. A $10 million contractor keeping $300,000 after all expenses operates at a 3% net profit margin.
Many contractors overestimate their real construction profit margins because they confuse gross profit on a job with true net profit. Gross profit covers only direct costs (labor, materials, subs, equipment). It does not account for office staff salaries, insurance premiums, technology, vehicles, rent, or compliance costs, all of which erode the number before it becomes net profit. The average net profit margin for construction ranges from 2% to 20% depending on trade, scale, and market. Top-performing specialists achieve profit margins of 8% to 15%, while most firms cluster far lower. A good net profit margin for construction should be above 5%.
The cost buckets that drain margin include:
- Material costs and waste
- Field labor and overtime
- Subcontractor performance and coordination
- Equipment rental and fuel
- Indirect costs (supervision, site logistics)
- Overhead (office, insurance, technology)
Construction project size directly affects overhead costs and profit margins; a firm running three $1 million jobs faces different overhead recovery dynamics than one managing a single $10 million project. Small percentage errors compound quickly. Underestimating material costs by 3% and field labor by 5% on a $5 million project creates a $400,000 gap, enough to consume what was supposed to be a profitable job.
Increasing profitability is less about chasing higher markups on every bid and more about consistently preventing profit leakage across estimating, procurement, and project delivery.
Material Costs and Moving Material Prices: The 2026 Reality for the Ohio Valley
Construction material prices remain volatile in 2026, especially for steel shapes, reinforcing bar, copper conductors, electrical switchgear, roofing membranes, insulation, and mechanical equipment used on Ohio Valley commercial and industrial jobs. Material price volatility affects profit margins in construction contracts because contractors lock in a price at bid time but purchase materials weeks or months later at whatever the market demands.
The BLS Producer Price Index for nonresidential construction inputs remains well above 2019 levels. Construction materials costs reached an all-time high of 354.9 in 2026, and even residential construction saw material costs rise 4.2% year over year. Tariffs can also keep import-sensitive inputs elevated, so contractors should know the country of origin on exposed materials. Year-over-year growth has slowed relative to the peaks of 2021 and 2022, but the absolute price level remains elevated enough to punish any bid built on outdated assumptions.
This environment affects job-level profitability in specific ways:
- Supplier quotes that expire in 30 to 60 days, forcing re-pricing after bid submission
- Unexpected freight surcharges along the I-75 corridor
- Long lead times for switchgear on healthcare or manufacturing projects around Dayton and Lima
- Rebar and structural steel availability that shifts month to month
- Substitution costs when specified products are unavailable
Close coordination with suppliers helps teams anticipate quote changes and lead-time issues.
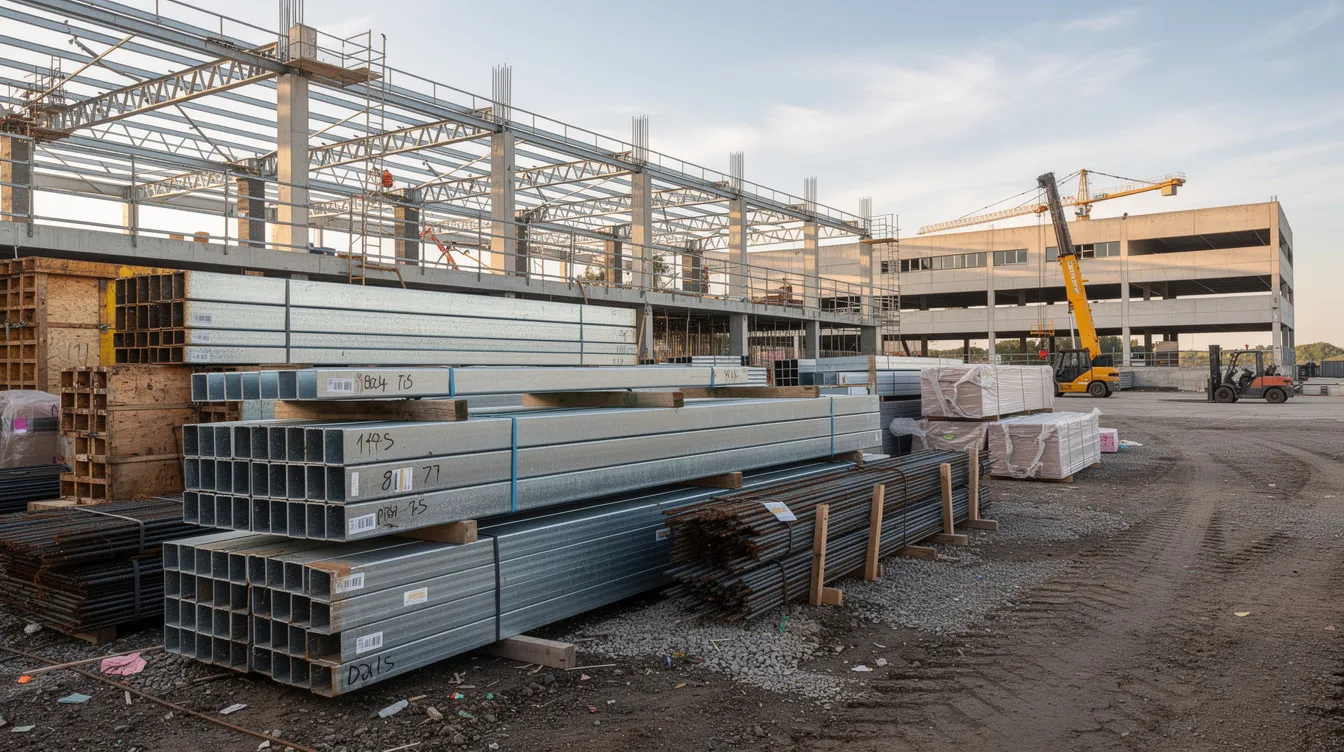
Controlling material costs is not only about securing the cheapest unit price. It is about timing, contract terms, supplier coordination, and procurement discipline that support the company’s net profit margin across the full project timeline, including understanding impact costs tied to procurement timing and sourcing.
Where Bids Go Wrong: Common Estimating and Procurement Mistakes That Kill Net Profit
Many profitable projects on paper become break-even jobs when original estimating assumptions do not align with actual material prices, labor productivity, or scope growth. Accurate estimating is critical for competitive, profitable bids, yet the same avoidable mistakes appear on job after job.
Common estimating failures include:
- Using stale supplier quotes or outdated price books that do not reflect current producer price trends
- Underestimating material waste (overages for cuts, damage, spoilage)
- Assuming best-case labor productivity despite known labor shortages in the market
- Carrying thin contingency on volatile trade packages
Procurement missteps compound the damage. Delaying buyout until after notice to proceed, failing to lock in pricing during the bid period, relying on a single supplier for critical path materials, and not clarifying alternates and allowances all contribute to lost profit. Subcontractor engagement should be early and structured; waiting until post-award to confirm sub pricing invites scope gaps and re-pricing.
Proactive risk management, including formal risk assessment during preconstruction for volatile material packages, helps avoid costly delays in construction projects. Yet few contractors model worst-case scenarios during preconstruction, such as what happens to net profit margin if key material prices jump 5% to 10% after bid day. Approval delays and unclear instructions also erode profit when field teams wait for answers and costs accumulate.
Consider a Springfield contractor who bids a school renovation at a 3% net profit margin. Roofing membrane and mechanical equipment costs surge after bid submission due to supply constraints. Without escalation language or price protection, the contractor absorbs the overrun, pushing the final result to zero or a loss. That scenario plays out across the Ohio Valley every quarter.
Building a Smarter Bid Strategy for Construction Profitability in 2026
Construction profit margins in the Ohio Valley improve when contractors replace a “price to win and hope it works out” approach with structured, data-driven bid processes. A balance of detailed planning and execution is essential for construction profitability, and the bid is where planning starts.
Practical steps for smarter estimating:
- Update key material and labor unit costs at least quarterly, with monthly checks on volatile items like steel, copper, and electrical gear
- Validate supplier quotes within days of bid submission, not weeks before
- Check recent producer price trends for relevant commodity categories before finalizing estimates
- Build strong bids around clear win themes and project specifics rather than generic templates
Pre-bid research significantly improves win probability, and successful contractors win only 20% to 30% of bids pursued. That means most firms invest significant estimating resources on work they will not win. Disciplined bid/no-bid decisions protect margins and resources by screening out projects where owner reputation, design completeness, schedule realism, or payment terms signal elevated risk.
Link bid markups to risk exposure, not just workload. A design-build industrial project in Northern Kentucky with heavy material content and a 14-month schedule warrants a higher target net profit margin than a short-duration commercial interior fit-out in downtown Cincinnati. Strong supplier relationships can reduce material costs and influence construction profitability by providing better pricing, longer quote validity, and priority delivery on competitive bids.
Practical tools that support a smarter pricing strategy include standardized estimating checklists, internal review gates before major bids are submitted, and post-project “lessons learned” sessions that feed actual cost data back into the estimating database for the next project.
Contracts, Escalation Clauses, and Sharing Material Price Risk With Owners
In a volatile cost environment, the contract is often the single biggest determinant of whether a contractor keeps their planned net profit margin, especially when rapid price swings put added pressure on preserving it. Properly structured contracts can shift risk and directly impact project profitability.
Contract types carry different risk profiles:
| Contract Type | Material Price Risk | Best Suited For |
|---|---|---|
| Fixed-price (lump sum) | Contractor absorbs all risk | Short-duration, well-defined scope |
| Cost-plus | Owner absorbs price changes | Complex, evolving scope |
| GMP (Guaranteed Maximum Price) | Shared risk with caps | Mid- to large-scale commercial/industrial |
Well-drafted escalation clauses tied to objective indices, such as specific BLS Producer Price Index categories for steel or concrete, can allow adjustments for extraordinary material cost increases while maintaining fairness to owners. Effective risk management minimizes costly mistakes by ensuring both parties understand triggers, caps, and notice requirements before ground is broken.
Use material allowances, unit pricing, or alternates in bids to clarify assumptions on volatile or long-lead packages like roofing, electrical switchgear, or specialty metals. A professional Quantity Surveyor can identify risks and manage change on complex projects with high material exposure.
Contractors should review standard contracts and owner-drafted forms with construction-savvy legal counsel, focusing on clauses that govern price changes, substitutions, schedule impacts, and dispute resolution. These provisions directly affect ultimate construction profitability and should never be treated as boilerplate.
Labor Shortages, Productivity, and Their Impact on Construction Profit Margins
The Ohio Valley faces a 60,000-worker labor shortage, with the gap most acute in trades like electrical, HVAC, concrete finishing, and mechanical equipment installation. Labor shortages increase installation times and project costs across every project type, from healthcare facilities in Dayton to logistics centers along I-75.
Labor productivity is a major cost factor in construction and significantly influences profitability. When crews are short-staffed or less experienced, installation durations stretch, generating more rental days, supervision hours, and indirect costs. Labor shortages can increase overtime costs by 15% to 20% and contribute to rising material costs through delays, as stored materials are exposed to damage, theft, or price movement while waiting for installation.
Workforce management and productivity tracking directly dictate labor cost efficiency in construction. Strategies that support increasing profitability include:
- Building estimates on historical productivity data, not optimistic assumptions
- Cross-training crews to increase flexibility across trades
- Using prefabrication and off-site assembly where feasible to reduce on-site labor hours
- Coordinating subcontractors and staffing plans early in preconstruction
ABC Ohio Valley’s apprenticeship and workforce development programs help members build a more stable workforce over time. Programs across nine trades, from electrical and HVAC to sheet metal and pipefitting, improve predictability in both material usage and labor costs. Contractors who track labor performance across similar project types and feed that data back into future bids avoid repeating the optimistic assumptions that have historically eroded margins.
Operational Discipline: Tracking Jobs in Real Time to Protect the Bottom Line
Protecting construction profitability requires real-time visibility into how each project is performing against its estimate. Construction companies that leverage technology can improve project profitability by better managing costs, schedules, and resources while tracking process improvements that lift profitability. Real-time data tracking helps identify labor overruns and material price spikes before they become unrecoverable.
Best practices for job-level cost control:
- Compare budget to actuals weekly or monthly by cost code, flagging overruns in materials, labor hours, or subcontractor costs early
- Effective communication among project teams reduces rework and improves project outcomes; field and office must review cost reports together
- Change order management is critical to avoid uncompensated labor and material costs; document, price, and seek approval for every scope addition
- Effective project management can control costs and reduce delays when leaders act on variance data rather than waiting for the final job report
Tight cost control and effective scheduling are vital for maintaining profitability in construction. Continuous monitoring of project performance can help identify profitability issues early, before small negative variances accumulate into a loss.
Cash flow management is crucial because construction projects often involve delayed payments. Delayed payments can significantly reduce profits, and many contractors report average days sales outstanding (including retainage) near 83 days. Late payments from owners or general contractors compress cash flow and force businesses to carry financing costs that eat into net profit.
Even small and mid-sized general contractors along the I-70 and I-75 corridors should establish a simple monthly “profit review” meeting where leaders review active jobs, work-in-progress schedules, and forecasted net profit margin for the year. That single discipline can be the difference between staying competitive and treading water.
Regional Factors That Shape Construction Profitability in the Ohio Valley
Regional market conditions shape construction profitability across Southwest and West Central Ohio, Northern Kentucky, and Southeastern Indiana. Strong demand in sectors like light manufacturing, logistics, healthcare, and higher education between Cincinnati, Dayton, Springfield, and Lima keeps backlogs healthy but also intensifies competition for materials, labor, and key subcontractors.
Localized supplier networks, freight distances, and plant locations along I-75 and I-70 influence delivered material prices and lead times. Two projects 100 miles apart can have meaningfully different cost dynamics based on which fabrication shops, distributors, and delivery schedules serve each area.
Tri-state regulatory and tax differences between Ohio, Kentucky, and Indiana subtly affect overhead and compliance costs. State sales and use tax treatment of construction materials, workers’ compensation rates, and licensing requirements must be reflected in overhead recovery rates when calculating net profit margin. Contractors who build region-specific data sets on material prices, supplier performance, and labor productivity make more informed decisions than those relying on national averages or outdated rules of thumb.
Using ABC Ohio Valley Resources to Improve Construction Profitability
ABC Ohio Valley has served merit-shop contractors for more than 50 years, helping members across the region improve construction profit margins through better information, training, and workforce development.
Education and professional development offerings strengthen estimating, project management, and financial literacy, skills that directly impact net profit and risk management. Job site safety protocols can impact profitability by reducing accidents and claims; safety programs such as STEP and Mid-America OSHA training help lower injury-related costs, lost time, and insurance premiums, all of which contribute to long-term profitability.
Workforce programs, including apprenticeship pathways with partners like Diamond Oaks and Sinclair Community College, address labor shortages and stabilize productivity. A more stable, skilled workforce improves schedule predictability and reduces the waste, rework, and overtime that erode margins.
Contractors from Cincinnati, Dayton, Springfield, Lima, Northern Kentucky, and Southeastern Indiana can engage with peer groups, roundtables, and chapter events where leaders share real-world strategies for protecting profit margins in the current market.
Next Steps: A Practical 30-Day Plan to Strengthen Your Construction Profit Margins
The contractors who protect margin in 2026 are the ones who treat estimating, procurement, and project controls as competitive advantages, not afterthoughts. Here is a concrete, time-bound action plan any mid-sized contractor in the Ohio Valley can start this month.
- Review your last three large bids within the next two weeks. Check material pricing assumptions against current data, evaluate contingency levels, and audit contract language on escalation and change orders. Document any gaps that could threaten net profit margin on active or upcoming work.
- Form a small internal task force including estimating, project management, and finance. Update standard estimating checklists, bid review procedures, and procurement timelines based on 2026 material price realities and supplier lead times.
- Schedule a strategic meeting with key suppliers to discuss forecasted material prices, delivery windows, and options for locking in pricing or using alternates on your next project.
- Establish a monthly profit review meeting if you don’t already have one, covering active job performance, WIP, and year-end net profit forecasts.
- Contact ABC Ohio Valley for information on relevant training, workforce development support, and member programs that can help your construction business strengthen operational discipline and long-term construction profitability.
The challenges in this market are real, but contractors and home builders who build discipline into every bid, every buyout, and every monthly review are the ones running a profitable business at year-end.
FAQ: Construction Profitability in the Ohio Valley
Below are answers to common questions about this topic.
How often should we update our material and labor rates in estimates?
In 2026, many Ohio Valley contractors should formally review and update key material and labor rates at least quarterly, with more frequent checks (monthly or by bid cycle) on volatile items such as steel, copper, roofing membranes, electrical gear, and specialized mechanical equipment. Build a simple internal calendar tied to BLS data releases and major supplier price bulletins so estimators are never working from rate sheets older than 90 days. Very long-duration projects, such as major industrial or institutional builds, may warrant scenario modeling of multiple cost paths rather than a single static rate to account for how material prices may move over project timelines.
What is a healthy net profit margin target for commercial contractors in this region?
Many general contractors historically operate between 1.5% and 5% net profit margin, but in a volatile cost environment, aiming for at least the upper end of that range is prudent. For home builders, target ranges may differ because product mix, cycle times, and buyer expectations differ from commercial work. When project risk is elevated, such as heavy material exposure or compressed schedules, the target should be higher still. The “right” target depends on company size, overhead structure, trade mix, and risk appetite. Consistently hitting a modest but stable net profit is often safer than chasing occasional high-margin wins. Benchmark your own results over multiple years rather than relying solely on broad industry averages when setting margin goals.
How can smaller subcontractors protect their margins when negotiating with larger general contractors?
Subcontractors should clarify scope in detail, including inclusions, exclusions, and assumptions about material brands, lead times, and crew sizes, to avoid absorbing unexpected costs later. Seek fair payment terms, prompt change-order processing, and, where possible, escalation language for long-lead or high-volatility materials. Joining an industry association such as ABC Ohio Valley provides access to education, model contract language, and peer experience that can strengthen commercial negotiations and help smaller firms compete effectively.
When is it appropriate to walk away from a project on profitability grounds?
Contractors should consider declining opportunities when a combination of low fees, high material exposure, schedule compression, or poor contract terms makes it unlikely they will achieve their minimum acceptable net profit margin. Use structured bid/no-bid criteria that score owner reputation, design completeness, risk allocation, and resource availability so that walking away is a disciplined business choice, not a last-minute gut decision. In a tight labor market, tying up crews and overhead on low-margin or loss-making work crowds out better opportunities that align with long-term profitability goals.
What internal metrics should leadership track monthly to stay on top of profitability?
Track a concise dashboard that includes backlog quality, gross profit and net profit margin by project, forecast-at-completion versus budget, change-order recovery rates, and days sales outstanding. Break results down by market segment or geography (for example, Cincinnati versus Lima or Northern Kentucky) to identify where construction profit margins are consistently stronger or weaker. Use these metrics not just as historical reports, but as triggers for action: tighten estimating assumptions, revise overhead recovery, adjust pricing strategy for certain project types, or retrain project teams on cost control where needed.


